.png)
 5 hours ago
2
“It requires a little fortune, now, to buy a house, and every article of furniture costs about three times as much as it did ten years ago.” That complaint isn’t from a TikTok video or a Substack newsletter — it’s a line in a piece titled “The Men Won’t Propose,” published in 1866 in a health magazine called Hall’s Journal of Health, more than a century before anyone had coined the term “Gen Z.”
The quote opens a new report from the BCG Center for Macroeconomics, “The Kids Are Alright: The Timeless Angst Over Young People and Money.” Economists Philipp Carlsson-Szlezak, Paul Swartz, and Henry Rubin argue that the received wisdom about a failing, falling-behind generation doesn’t survive contact with the data: Gen Z, by their reckoning, is richer at the same age than Millennials, Gen X, or the Baby Boomers ever were.
Gen Z feels worse about money than any generation on record. A generation thriving by every number that matters and miserable anyway is the kind of contradiction Charles Dickens built a career on.
The best of times, the worst of times
We all know the opening lines from A Tale of Two Cities: “It was the best of times, it was the worst of times, it was the age of wisdom, it was the age of foolishness, it was the epoch of belief, it was the epoch of incredulity, it was the season of light, it was the season of darkness, it was the spring of hope, it was the winter of despair.”
That’s more or less the shape of the BCG data, according to Carlsson-Szlezak, the firm’s global chief economist. A huge chunk of his job is dedicated to tackling these persistent misperceptions of economic facts; his 2024 Shocks, Crises and False Alarms, co-authored with Paul Swartz, made the Financial Times‘ list of best economics books of that year, in part for arguing that narratives can be overblown and the fundamental data is always a better guide. “The all-too-common narratives of economic collapse and decline are often false alarms themselves,” the authors write of their approach — very similar to their take on Gen Z’s Dickensian paradox.
“I have empathy for Gen Z,” Carlsson-Szlezak told Fortune over email. “They were the guinea pigs of the smartphone revolution, and they had little help from parents and educators to build effective filters to distinguish TikTok from IRL.”
But at the same time, the facts don’t lie.
On income, Gen Z has opened the widest generational lead since the Boomers: the oldest Gen Z workers, at 28, earn a median $42,000 in constant dollars — 25% more than Millennials made at that age, and 50% more than Boomers did.
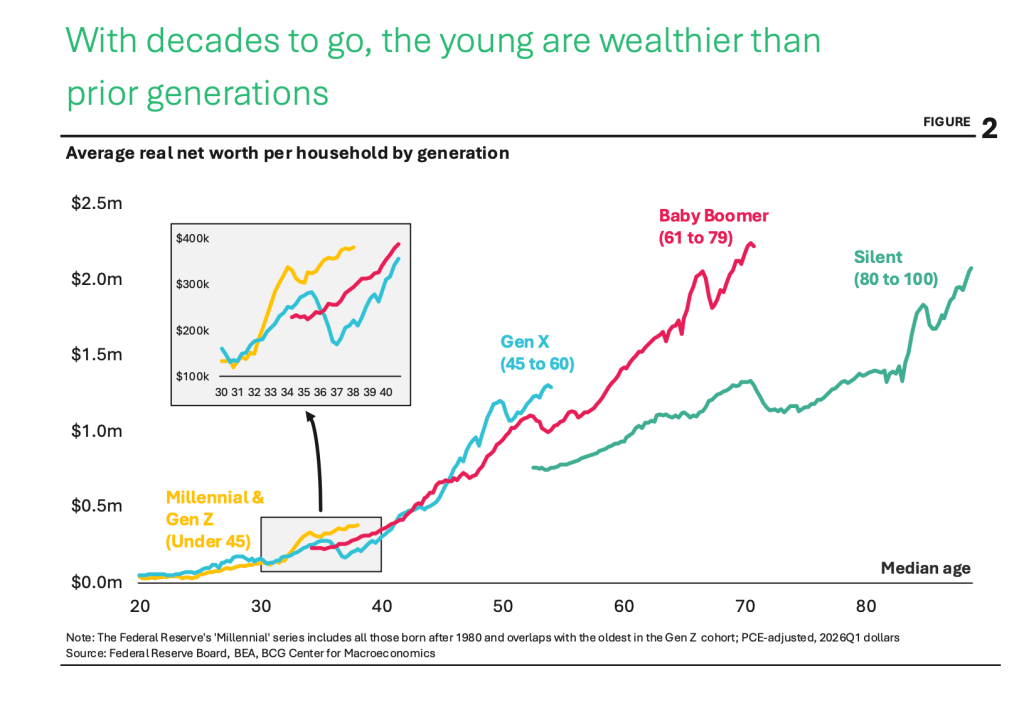
On wealth, BCG says Gen Z is too young on its own for meaningful comparisons. But when combined with Millennials, the report points out that today’s young have pulled ahead of prior generations. Millennials at 34 carry an average net worth of $331,000, versus $251,000 for Gen X and $229,000 for Boomers at the same age.
Sentiment has moved the opposite way. For the first four decades that pollsters tracked the question, older Americans were reliably gloomier about the economy than the young — a pattern that held from at least 1980, until it flipped around 2025. For the first time on record, the young are more pessimistic than the old. A fresh SoFi/YouGov survey of 4,090 U.S. adults lands on the same fault line: 62% of Gen Z and Millennials still aspire to retire comfortably, but only 46% believe they actually will. The SoFi report argues that Gen Z is “financemaxxing” and “lifemaxxing,” looking beyond financial returns to consider the “emotional ROI” of how far their money can go. The survey data confirms much of BCG’s argument, saying Gen Z has a case of great expectations and seems to be overlooking how well off they actually are.
The BCG authors hedge their own thesis. “Our analysis of generational progress is not a claim that all is well for all. Rather, it is a push back against the thin claims that all is wrong,” the report says. Student debt is real; city housing is genuinely more expensive; some in this generation will not out-earn their parents, as some didn’t in every generation before them.
“Gen Z and Millennials go through their own unique generational struggle to build careers, income, and wealth—and they are confronting unique challenges such as student debt and housing affordability,” the authors write, before concluding that “even so, they are making broad generational progress.”
Hard times, and whether they’re structural
The report’s sharpest rebuttal targets the “K-shaped economy” narrative — the idea that the rich are pulling away while everyone else falls behind. Since 2020, the authors find, wage growth for the bottom quartile has outpaced the top in nearly every year, and wealth gains have been roughly proportional across income quintiles.
And according to SoFi, 77% of Gen Z believe they can start a business, versus 58% of older generations, and Gen Z is four times more likely than Boomers to have invested in crypto (26% vs. 6%). Similarly, the young also hold a greater share of their assets in stock, but that leaves them more vulnerable to market swings.
“Greater equity exposure does raise the risk of Gen Z falling behind, cyclically, in a bear market,” Carlsson-Szlezak said, noting the dent that the 2008 financial crisis left in Gen X and Boomer wealth curves. But he argues the long-run bet still favors the young, since “expected equity returns outstrip most other asset classes” — and housing wealth, he notes, wasn’t immune to setbacks either in the 2000s and 2010s.
In a 2024 Empower survey cited by BCG, Gen Z said it would need to earn $600,000 a year to feel financially successful — the 99th percentile of U.S. income, versus Boomers’ self-reported bar of $100,000. The median full-time salary is around $60,000.
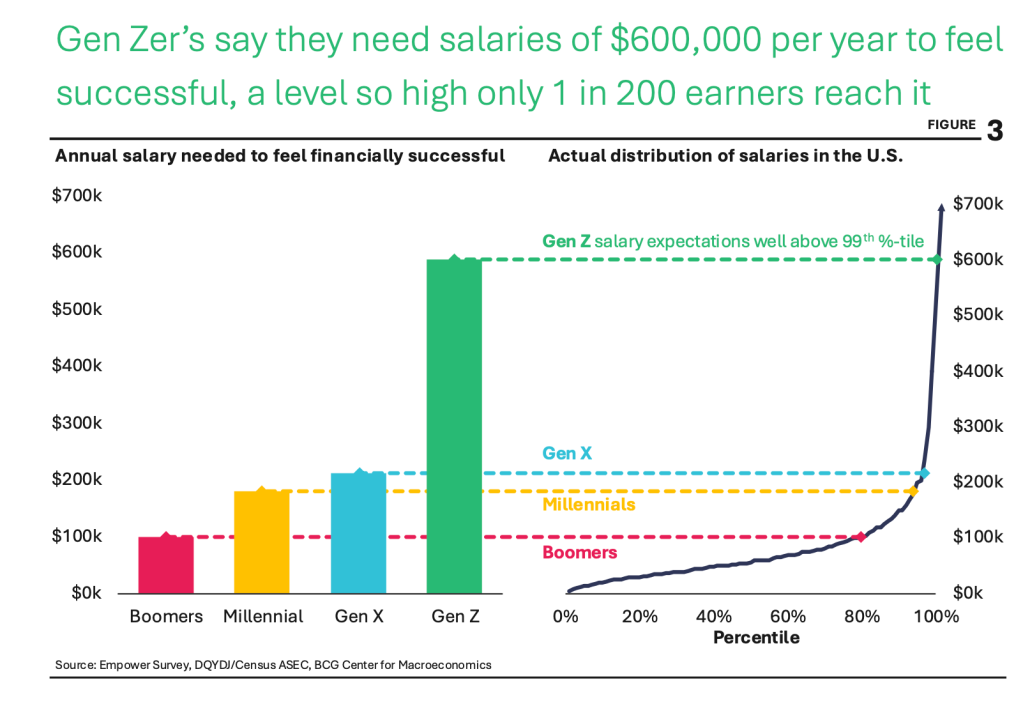
The authors call this gap “financial dysmorphia,” driven partly by social-media exposure to unrepresentative wealth. Still, they argue that financial dysmorphia should not be allowed to take root and continue to misperceive economic fact: “As the young reach adulthood, they are responsible for using effective filters to screen out digital bling and focus on the reality in front of them.”
Housing and Dickens
Housing is the report’s most granular finding, and the one place the “kids are alright” thesis meets real friction. It now takes nearly six years of median income to buy a median-priced home, up from three and a half in 1975 — but the median new home is also 50% larger, and square-footage-adjusted affordability has barely moved. The real bind, the authors argue, is that 90% of young people now live in cities and suburbs, chasing housing stock that isn’t being built fast enough.
Carlsson-Szlezak argued that preference is temporary, not fixed: “This preference peaks in the mid-to-late 20s, and a drift to the suburbs sets in. By age 42, many Millennials have moved to the suburbs, and that’s exactly when they catch up with Gen X in homeownership rate.”
Dickens knew something about the gap between fortune and a roof overhead. His father was imprisoned for debt in 1824, and 12-year-old Charles was sent to work 10-hour days pasting labels onto boot-blacking jars — a shame he told almost no one about for the rest of his life. His grandmother’s death left the family a small inheritance, enough to clear the debt. It’s more or less the plot of Great Expectations, whose hero Pip inherited a mysterious fortune, assumed it marked him for greatness, and spent the novel’s second half ashamed of the family that raised him. Dickens wasn’t sympathetic to this potentially autobigraphical delusion: the novel rewards Joe Gargery’s plain decency over Pip’s inflated aspiration.
David Copperfield, the hero of Dickens’s own favorite among his novels, is a more Boomer-coded anti-Pip: an orphan who rises out of poverty through work, patience, and a stubborn attachment to the people who were kind to him along the way, not through a windfall he didn’t earn. Where Pip’s fortune arrives by accident and corrupts him, David’s comes gradually and leaves him more or less intact. It’s the difference between a life built and a life inherited.
A journey, not a verdict
BCG’s own argument is that the Boomer boom was a fluke — yet Boomers remain the report’s baseline. “Boomers are the base compare culturally and in academia alike,” Carlsson-Szlezak says, noting they’re the only generation with a full lifecycle of data. The deeper point is about the size of the bar: “In terms of income progression or wealth accumulation, Gen Z can beat the Boomers. But it’s unlikely Gen Z can outperform Gen X by more than the Boomers outperformed the Silent and Greatest generations — just because that bar was so low.”
Carlsson-Szlezak acknowledged that Boomer prosperity can’t recur. “What’s not repeatable is the shift from single to double income households,” he said, pointing to women’s mass entry into the labor force — a one-time shift that, by definition, can’t happen twice. He raises a second, less obvious advantage: the generation Boomers were competing against. The Great Depression’s Silent generation, whose economic scars set a historically low bar for Boomers to clear.
Carlsson-Szlezak doesn’t think the gap closes easily. His more concrete hope is generational: “The current crop of teens are being weaned off their smartphones at least during school hours. Perhaps ‘peak financial dysmorphia’ is behind us.” A better understanding of history, including an appreciation of progress, would also help, he adds.
Pressed on which explanation carries the most weight — psychology, a flawed benchmark, or economic structure — Carlsson-Szlezak replied, “Nothing is ever monocausal, but the biggest challenge is that of distorted expectations, in my view.” And what does he think Charles would say of all these misplaced great expectations? “I think Dickens would look at Gen Z and say they should strive to be David but choose to be Pip.”
This story was originally featured on Fortune.com


 English (US) ·